
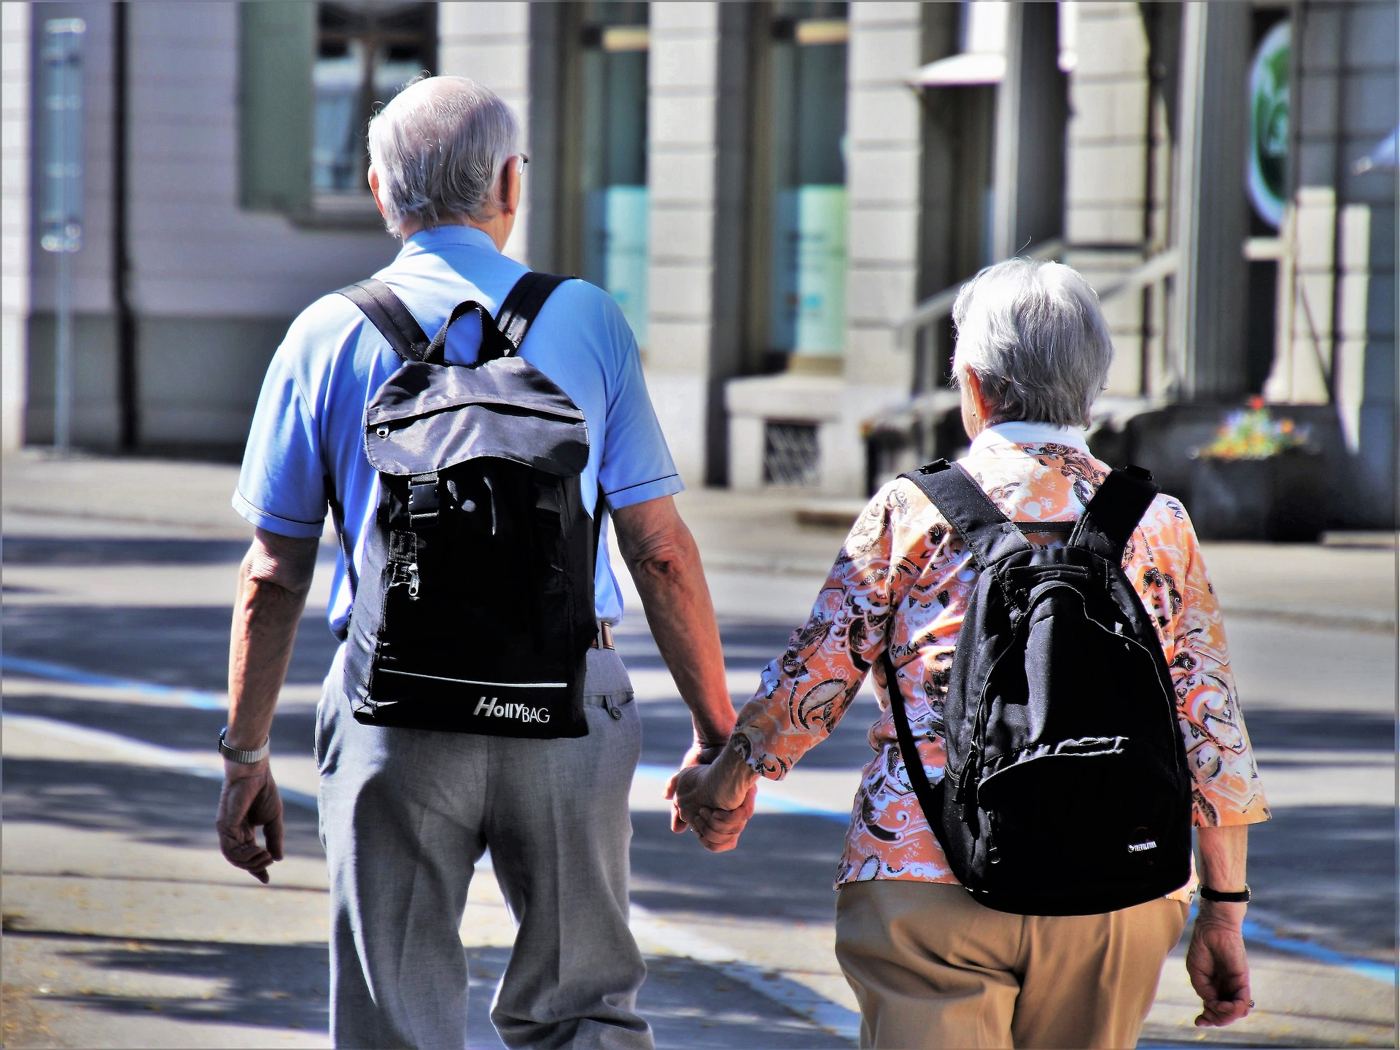
Retirement no longer has to be a single day when work stops completely. A growing number of experienced workers are choosing a phased approach, reducing their hours, dropping to part-time contracts, or moving into mentoring roles for a few years before stopping entirely. Financially, a gradual transition can soften the change in income, keep pension contributions going for longer, and delay the point at which savings must be drawn down. Personally, many people find that a staged departure helps them adjust to a new routine, test how they want to spend their time, and hand over knowledge to colleagues rather than leaving abruptly after decades in a role. Employers increasingly recognise the value too, since retaining skilled staff part time preserves experience that would otherwise walk out of the door in a single day.
What the Evidence Shows
Planning a phased retirement starts with honest conversations: with an employer about flexible options, and at home about how reduced hours would affect the household budget. Checking how part-time earnings interact with pension income and tax allowances is an important part of the picture, and the rules differ between schemes and countries. Some people use the freed-up days for caring responsibilities, volunteering, or training for a small second career. Others simply value a shorter week. Either way, the documents on the desk, statements, projections, and budgets, help turn a vague wish for a gentler pace into a workable timetable with dates and figures attached. Trying the reduced pattern for a defined trial period, where an employer allows it, gives both sides evidence about whether the arrangement works before it becomes permanent. Reporting and analysis from sources such as World Bank track the same developments, and specialists following phased retirement and part-time work say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, phased retirement and part-time work matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for phased retirement and part-time work hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
